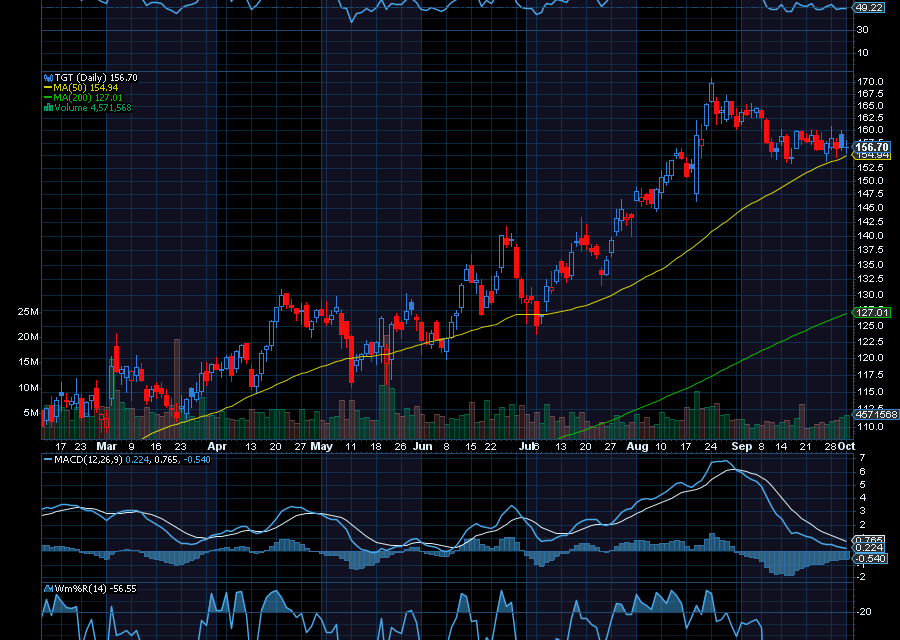
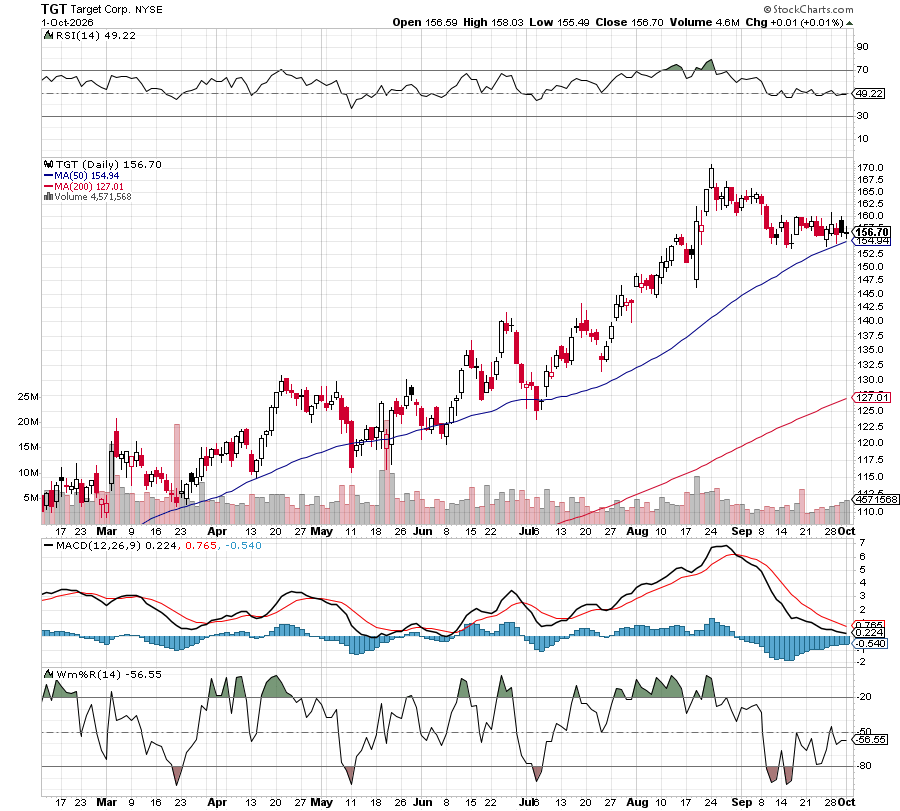
Target (NYSE: TGT) is giving investors more reasons to take its recovery seriously. Shoppers are returning, sales are improving, and HSBC believes the retailer could deliver stronger earnings than its forecasts currently suggest.
Analyst Joe Thomas upgraded Target to Buy from Hold and raised his price target to $190 from $125. Helping, Target’s recently reported second-quarter comparable sales increased 3.8%, including a 2.7% gain in store-originated sales. Comparable sales help investors evaluate growth across an established retail business without relying on expansion through new locations.
HSBC highlighted that growth came primarily from increased customer traffic rather than higher spending per transaction. In other words, Target’s improvement reflects more shopping activity, which gives the recovery a stronger foundation.

The Recovery Has Room to Run
According to HSBC, beauty, food and beverage, and household essentials are showing improvement. Apparel and home remain areas where Target has more work to do. There are encouraging signs, however. The analyst highlighted double-digit growth in back-to-school apparel, suggesting customers will respond when Target gets its merchandise and value proposition right.
Target is also sharpening its marketing and putting more than $2 billion in incremental investment toward improving the shopping experience, according to the HSBC note. The challenge is making those investments productive. Better merchandise, more appealing stores, and competitive prices need to translate into repeat visits and profitable purchases.
Why HSBC Thinks Earnings Could Keep Improving
Thomas raised his fiscal 2027 earnings estimate to $10.61 per share from $8.26. HSBC also sees potential for operating margins to reach around 6%, depending on how much sales recover. These are analyst forecasts, rather than guaranteed outcomes.
The logic is straightforward. Retailers carry expenses such as store leases, equipment, and management that don’t necessarily rise at the same pace as sales. When revenue grows, those costs can be spread across a larger sales base.
That can allow profits to increase faster than revenue. However, price reductions, promotions, and investments in stores can absorb some of those gains. Investors should watch whether Target can attract customers while protecting profitability.
The Dividend Adds Another Reason to Watch
Target’s board also declared a quarterly dividend of $1.16 per share, payable December 1, 2026, to shareholders of record November 11. It will mark the company’s 237th consecutive dividend since becoming publicly held in 1967.
At the current quarterly rate, that works out to $4.64 per share annually. The payment gives shareholders income while they assess the recovery’s progress. Target’s investment case ultimately comes down to consistency. One encouraging quarter can lift sentiment, but sustained traffic growth, healthier merchandise categories, and stronger underlying earnings would make a more convincing case.
Sincerely,
Ian Cooper




Recent Comments