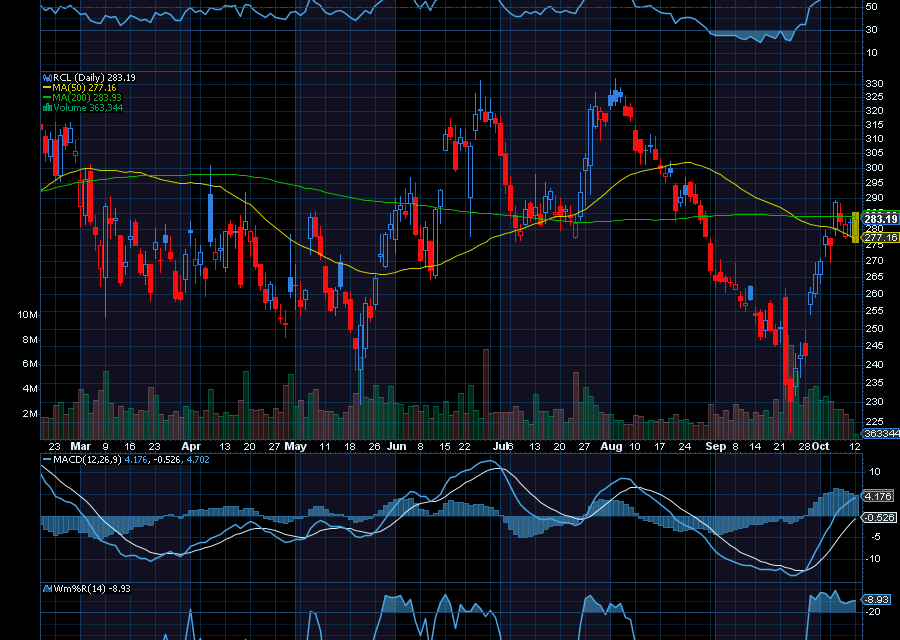
Royal Caribbean (NYSE: RCL) is giving investors many more reasons to take a closer look. With third-quarter earnings approaching later this month, expectations for continued profit growth, fresh analyst upgrades and a major investment in Sandals Resorts are putting the cruise operator back calmer waters.
The company, whose cruise brands include Royal Caribbean International, Celebrity Cruises and Silversea, is scheduled to discuss its third-quarter results on October 27. Investors will be watching both its performance and what management says about the months ahead.
Earnings Expectations Remain Encouraging
Analysts expect Royal Caribbean to deliver quarterly earnings of $6.36 per share, up about 10.6% from adjusted earnings of $5.75 a year earlier. That would put the company at the upper end of its previously announced third-quarter adjusted earnings guidance of $6.26 to $6.36 per share. The company has beaten consensus estimates in three of the past four quarters. Another strong result would help reinforce the argument that its business remains resilient despite concerns surrounding the travel industry.
The longer-term estimates also suggest the growth story has room to continue. Analysts expect earnings of $17.79 per share for fiscal 2026, compared with $15.64 in 2025. For 2027, expectations rise to $20.11 per share, representing another roughly 13% increase.
Deutsche Bank Sees an Overdone Selloff
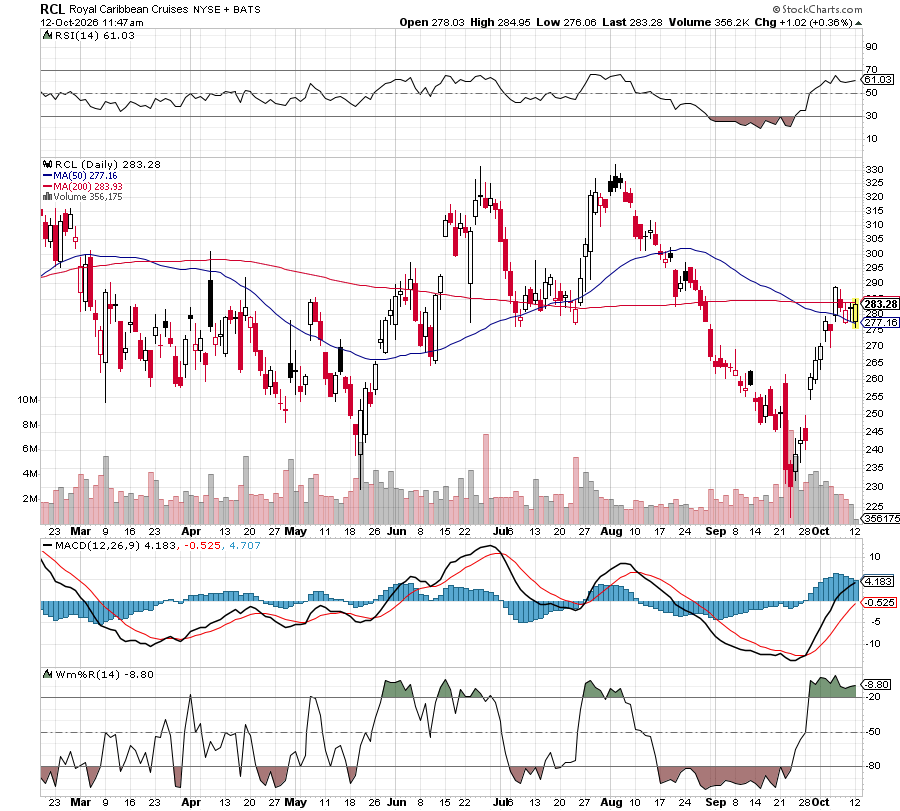
Deutsche Bank analyst Chris Woronka upgraded the stock to Buy and assigned a $299 price target. Before that rebound, the stock had fallen more than 20% from its early-August peak. Higher oil prices and questions about cruise demand had made investors nervous.
Woronka’s argument is that those concerns have become too heavily reflected in the share price. He noted that fuel represents approximately 7% of revenue and pointed to encouraging results from competitors as evidence that travelers are still spending. The implication is that cruise operators may have some ability to offset higher expenses through stronger pricing.
Jefferies analyst David Katz also sees meaningful potential the company’s $3 billion agreement in taking a 50% stake in Sandals. He upgraded Royal Caribbean to Buy from Hold and raised his price target to $330 from $305, implying nearly 17% upside from the Wednesday closing price referenced in his report.
Sincerely,
Ian Cooper



Recent Comments