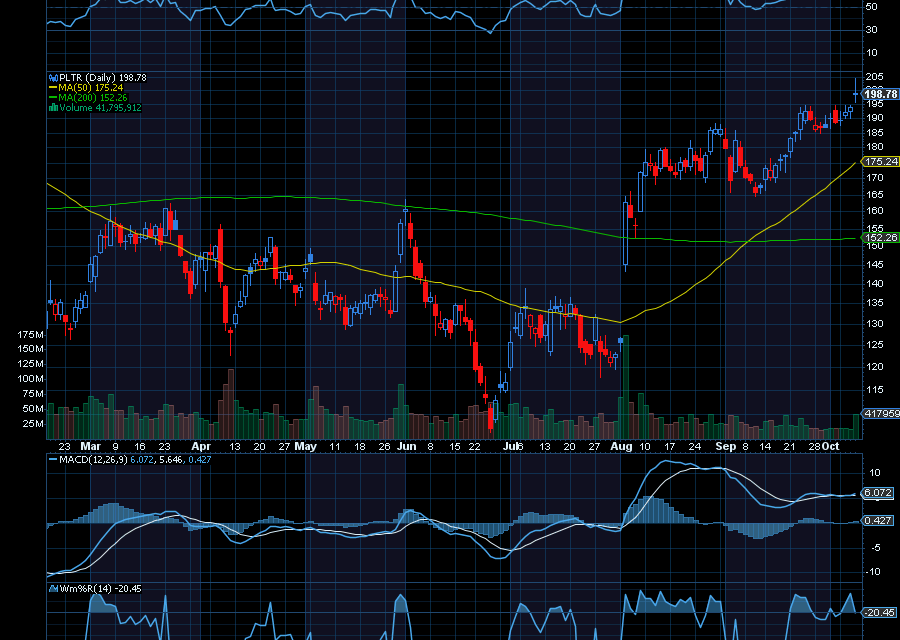
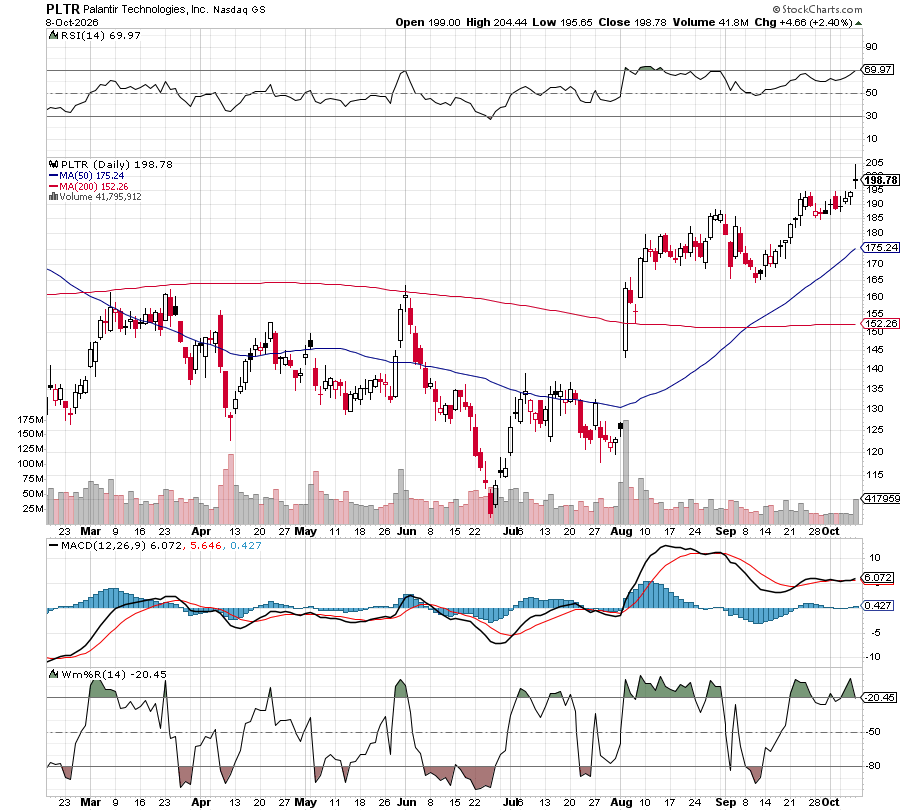
Palantir Technologies (NASDAQ: PLTR) could see even more upside thanks to AI, according to Goldman Sachs. In fact, the firm just upgraded the software company to Buy from Neutral, arguing that its recent stock underperformance has created a more attractive opportunity.
Analyst Gabriela Borges also increased her Palantir 12-month price target to$230, arguing that the company’s potential market could expand further. Borges framed the debate around Palantir’s nearly $8 billion annualized revenue run rate and roughly 100% growth rate, as described in her notes. Those figures help explain both the excitement surrounding the business and the questions about what comes next.
Recent Earnings and Guidance have also been Strong
In its most recent quarter, the company posted EPS of 41 cents, beating estimates by six cents. Revenue of $1.94 billion, up 94% year over year, beat by. $130 million.
“Demand for AI sovereignty has now been unleashed. And Palantir is the only company that has demonstrated it can transform tokens into actual economic value. Our customers trust us to provide them with maximal control over their operations, data, and decisions. Their competitive advantage should never become the training data for future models. This quarter was otherworldly: our U.S. commercial revenue grew 149% year-over-year, our overall revenue grew 93% year-over-year, and our Rule of 40 score climbed to 155%. The sovereign AI revolution makes us very optimistic about the future,” added Alex Karp, Co-Founder and Chief Executive Officer of Palantir Technologies.
Looking ahead to the third-quarter, Palantir expects revenue to be between $2.16 billion and $2.164 billion, above the $2 billion estimate. Adjusted operating profit during the period is expected to be between $1.29 billion and $1.3 billion, above the $1.14 billion estimate. For the full-year, Palantir now expects sales to be between $8.15 billion and $8.16 billion, above the previous range of $7.65 billion to $7.66 billion.
Sincerely,
Ian Cooper



Recent Comments