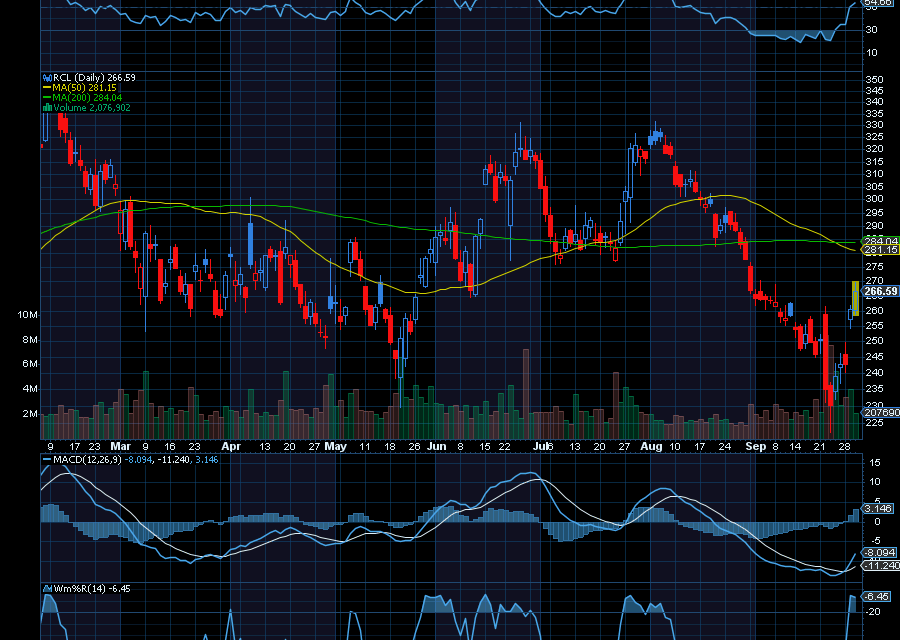
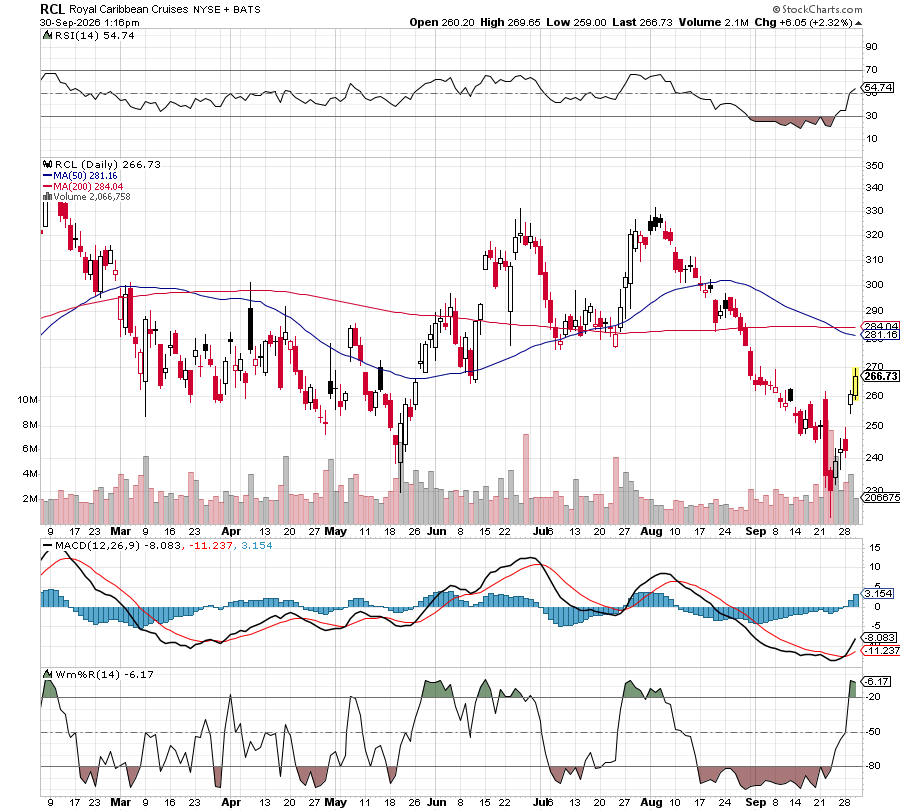
Keep an eye on oversold shares of Royal Caribbean (NYSE: RCL).
Bank of America and Deutsche Bank believe Royal Caribbean Group (NYSE: RCL) may now offer an opportunity. In fact, both firms upgraded the cruise stock to Buy after a sharp pullback. Bank of America maintained its $330 price target, while Deutsche Bank kept its target at $299. Their argument is straightforward: The shares have become cheaper, while demand for the company’s vacations appears to be holding up.
Bank of America believes the underlying business remains strong. Its analysts pointed to returns on invested capital in the high teens and EBITDA margins approaching 40%. Those figures suggest Royal Caribbean is generating substantial earnings from its operations and putting the money invested in its business to productive use.
Perhaps the most encouraging part of the analysts’ case is that consumers still appear willing to spend on travel. Bank of America said travel spending has grown at a mid- to high-single-digit rate since February. Cruise spending showed even stronger momentum, accelerating to growth in the mid-teens during July and August.
In addition, comments from Royal Caribbean at a recent Bank of America conference also gave the bank confidence in the company’s outlook. Its analysts expect fourth-quarter 2026 net yield growth of at least 4%, which they believe would lead the industry. Looking ahead, Bank of America believes Royal Caribbean could guide for 2027 net yield growth of 2% to 3%, consistent with its historical framework.
In addition, there is also a new piece to the growth story: Royal Caribbean’s announced $3 billion investment for a 50% stake in Sandals Resorts. Bank of America estimates the transaction could add 3% to 4% to EBITDA in the near term. Beyond that initial contribution, the bank sees opportunities for Royal Caribbean to help improve the resort business through its pricing experience, purchasing capabilities and loyalty program.
Sincerely,
Ian Cooper




Recent Comments