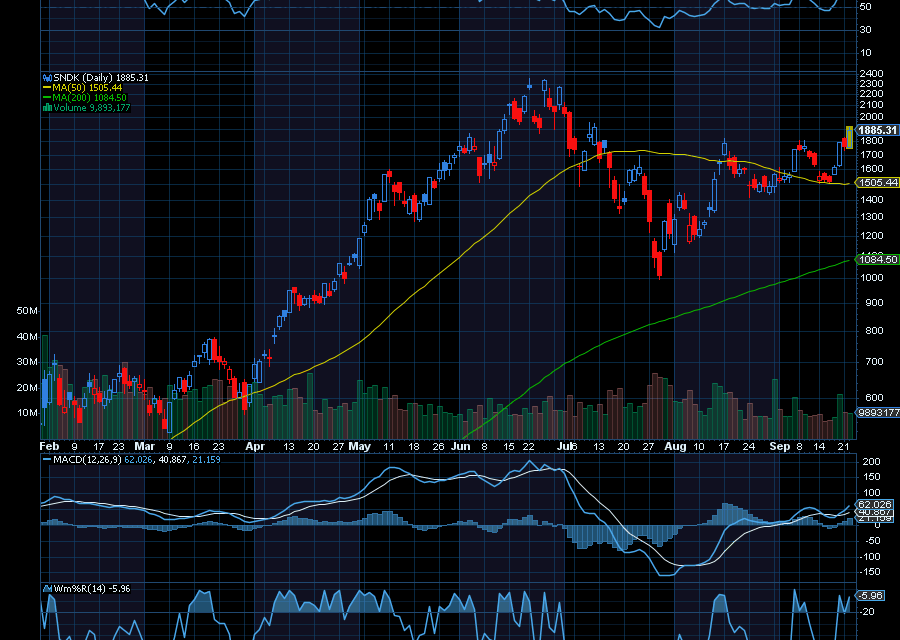
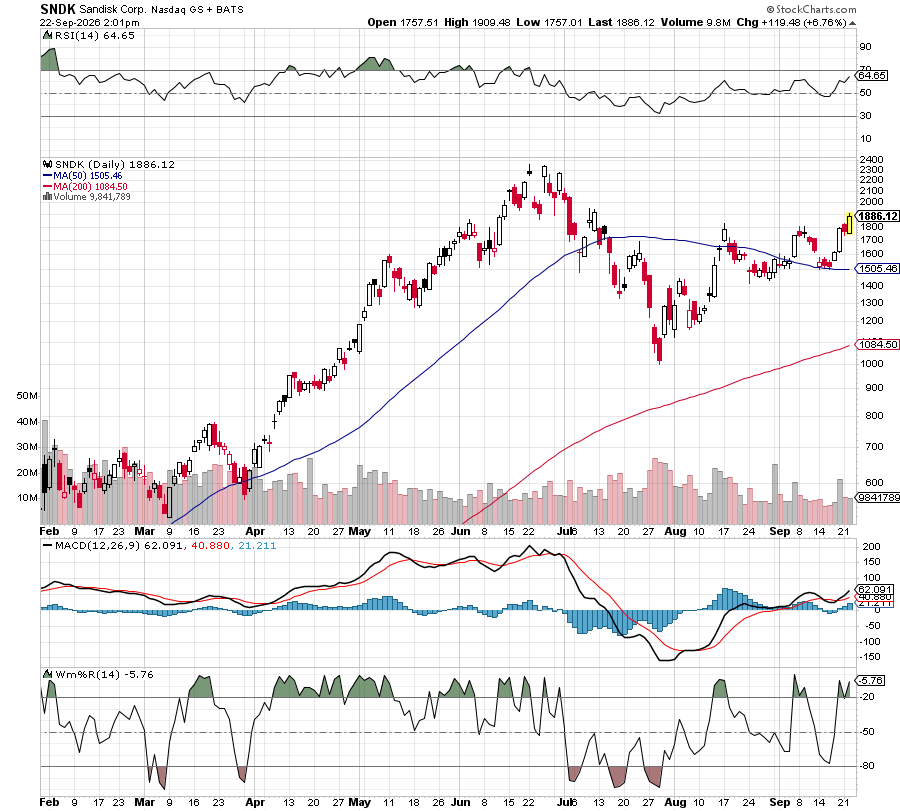
Sandisk (NASDAQ: SNDK) already delivered strong performance in 2026. However, analysts Rosenblatt believes the data-storage company’s rally may still have room to run. The firm just initiated coverage of Sandisk with a buy rating with a price target of $2,400.
That may sound like an aggressive call, especially after Sandisk shares surged more than 600% since the beginning of the year. But Rosenblatt analyst Kevin Cassidy believes artificial intelligence is changing the importance of the company’s core technology.
Instead of viewing NAND flash memory as a basic, interchangeable storage product, investors may need to start seeing it as an increasingly important component of AI infrastructure.
Sandisk May Have a Technological Advantage
Rosenblatt also believes Sandisk’s technology can help separate the company from its competitors. The firm pointed specifically to Sandisk’s BiCS8 and BiCS10 3D NAND platforms.
Three-dimensional NAND allows manufacturers to stack layers of memory cells vertically, increasing the amount of information that can be stored without requiring a proportionate increase in the physical size of a chip.
That matters because AI data centers need increasingly large amounts of storage while still attempting to manage space, power consumption and operating costs.
Sandisk says its BiCS10 technology uses 332 memory layers and offers a 59% improvement in bit density compared with BiCS8. It can also deliver interface speeds of up to 4.8 gigabits per second, along with improved power efficiency.
Rosenblatt believes that combination could give Sandisk an attractive cost curve while still providing the performance required by AI-oriented customers. From here, Rosenblatt’s $2,400 target suggests Sandisk can maintain a meaningful technological and cost advantage while benefiting from sustained AI-storage demand.
Sincerely,
Ian Cooper




Recent Comments