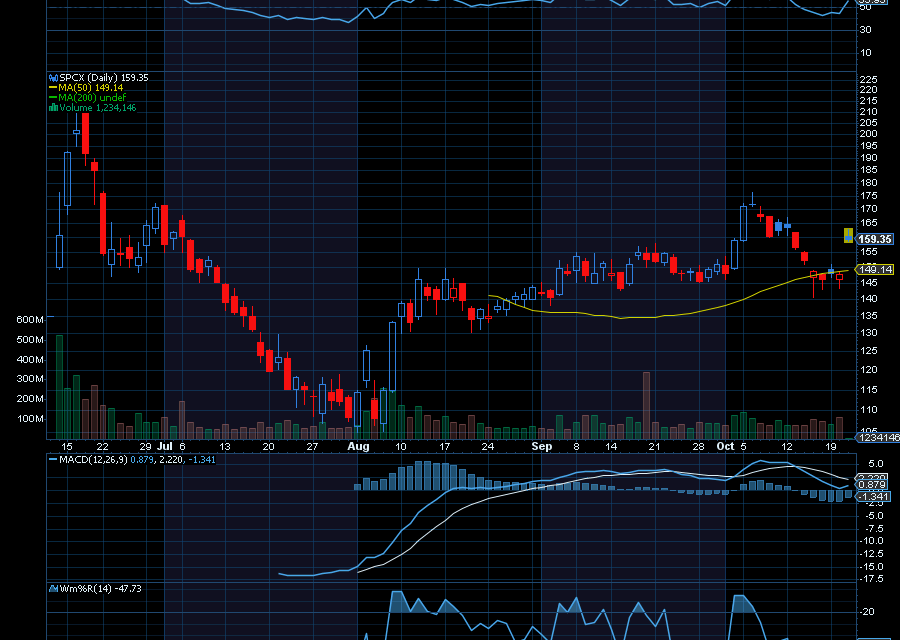
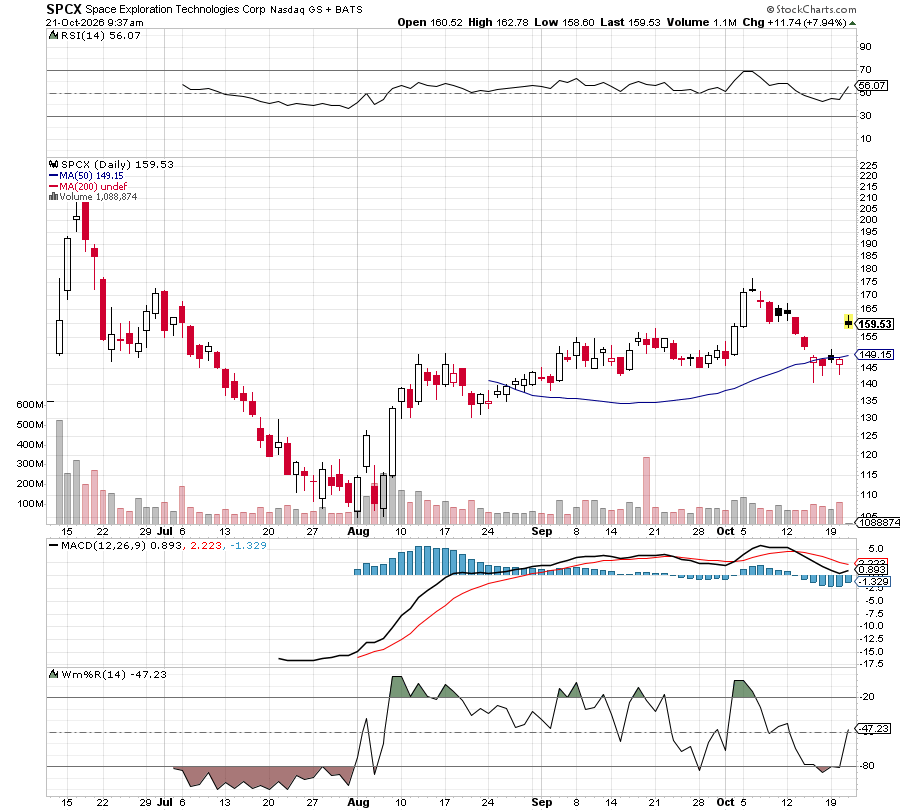
Keep an eye on SpaceX (SPCX).
After healthy earnings, analysts say it could see more upside.
In its most recent quarter, SpaceX generated $14.6 billion in third-quarter revenue, up 161% from a year earlier, a substantial increase. That also exceeded the $12.7 billion analysts expected. Adjusted earnings hit 45 cents per share, comfortably above the 13-cent forecast.
One of the clearest signs of progress came from Starlink.
The satellite internet business added 1.6 million consumer subscribers during the quarter, bringing its total to 13.6 million. That expanding customer base gives SpaceX a recurring source of revenue as subscribers pay for continued service.
In addition, SpaceX’s AI operations are another major reason why analysts are becoming more optimistic. Management pointed to growing adoption of Grok and additional cloud services agreements. Executives also outlined plans to reach volume production of AI-related chips through the Terafab collaboration with Tesla and Intel within two years.
With that, many analysts are out with bullish calls.
Wells Fargo, for example, sees SpaceX’s launch capabilities as an important advantage. Its argument is that controlling launches can help the company deploy infrastructure efficiently and support growth across its operations. The bank raised its price target to $274 from $214 while maintaining an overweight rating.
Wells Fargo isn’t the only firm that’s bullish. Barclays raised its price target to $300 from $254, while JPMorgan increased its target to $500 from $240. UBS and Citi also lifted their targets, reflecting confidence in the company’s combination of connectivity, computing and launch.
Sincerely,
Ian Cooper





Recent Comments