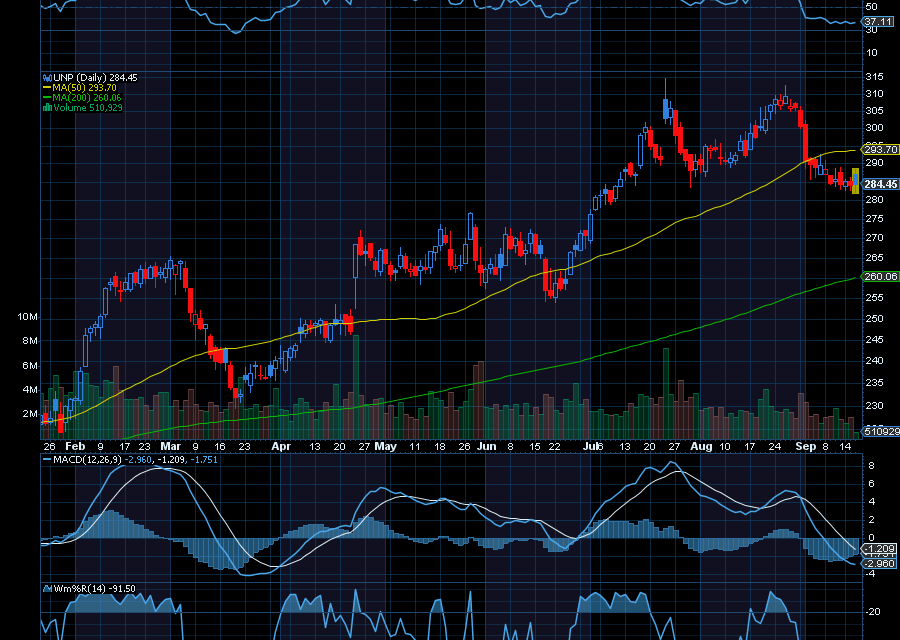
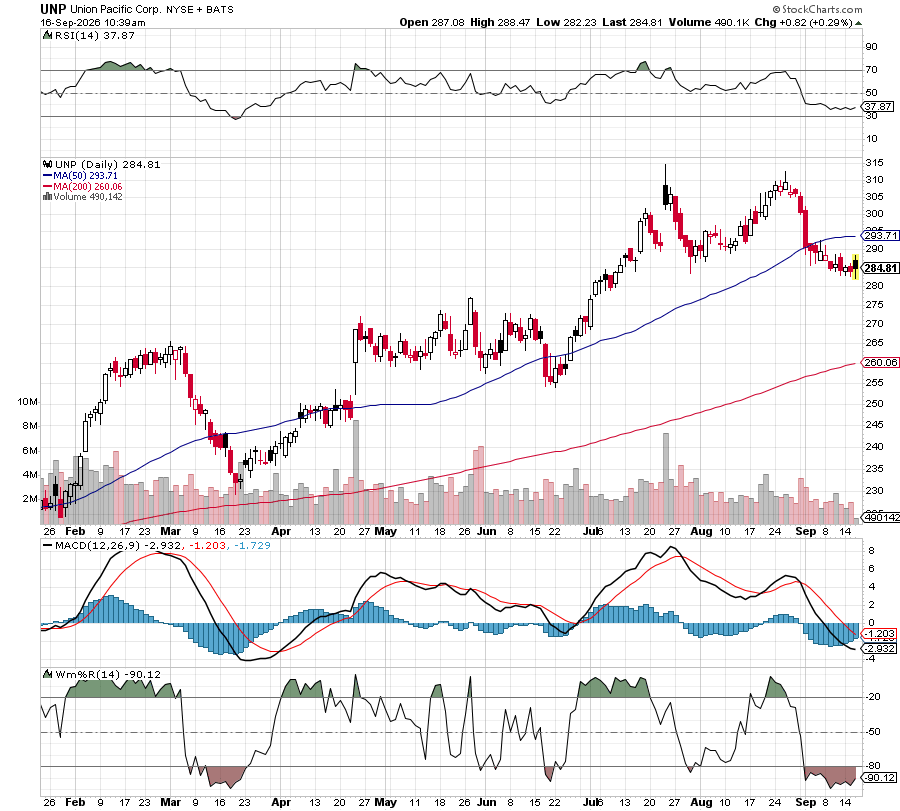
Union Pacific Corporation (NYSE: UNP) could have a strong year ahead, says UBS. The firm just upgraded the stock to a buy rating, with a price target of $339 from $310.
For one, UBS expects Union Pacific to benefit from growing freight demand, better pricing, and a possible merger with Norfolk Southern Corporation (NYSE: NSC). Together, these catalysts could help the railroad generate stronger revenue and earnings.
More Cargo Could Mean More Revenue
Union Pacific operates one of the largest railroad networks in the country. Its trains move goods across the western two-thirds of the United States. The company transports a wide range of products, including automobiles, chemicals, coal, grain, lumber, and consumer goods. It also carries shipping containers that arrive at major U.S. ports.
This makes Union Pacific an important part of the American economy.
When businesses produce and sell more goods, they need a way to move those products. That can create more business for Union Pacific. UBS analyst Thomas Wadewitz believes several of the company’s major markets are improving. His research suggests Union Pacific could enjoy a second consecutive year of strong freight growth in 2027.
Also, railroads are often more efficient than trucks when moving large amounts of cargo over long distances. That makes intermodal shipping an important growth market for Union Pacific.
If the company moves more containers across its network, it could generate more revenue without needing to build an entirely new railroad system.
Union Pacific May Also Charge Better Prices
Growing volume is only one part of the opportunity.
UBS also believes Union Pacific could benefit from better freight prices. This is especially important when comparing railroad rates with prices in the trucking industry. Railroads and trucking companies compete for many of the same customers. When trucking rates increase, shipping goods by rail can become more attractive. That can give Union Pacific more power when it negotiates contracts and prices with customers.
Better pricing could have a meaningful impact on profits.
Railroads have high fixed costs. Union Pacific must maintain its tracks, locomotives, terminals, and other equipment. It must also pay its workers and cover fuel costs.
Many of those expenses remain in place whether a train is completely full or only partly full.
As a result, adding more freight to existing trains can be highly profitable. If Union Pacific can move more cargo and charge higher rates, its earnings could grow faster than its expenses.
That combination is a major reason UBS became more bullish on the stock.
The Bottom Line
Union Pacific owns a railroad network that would be extremely difficult and expensive for a competitor to copy. That gives the company a strong position in the U.S. transportation market.
UBS believes the railroad could benefit from two powerful trends in 2027: more freight volume and better pricing.
If Union Pacific can carry more goods while keeping its costs under control, revenue and earnings could improve. The proposed Norfolk Southern merger could add even more long-term value, although approval is far from guaranteed. For investors, the story is fairly straightforward. Union Pacific already owns an important transportation network. Now it may be entering a period of stronger demand and improving prices.
If UBS is right, Union Pacific stock could have plenty of room to keep moving down the track.
Sincerely,
Ian Cooper




Recent Comments