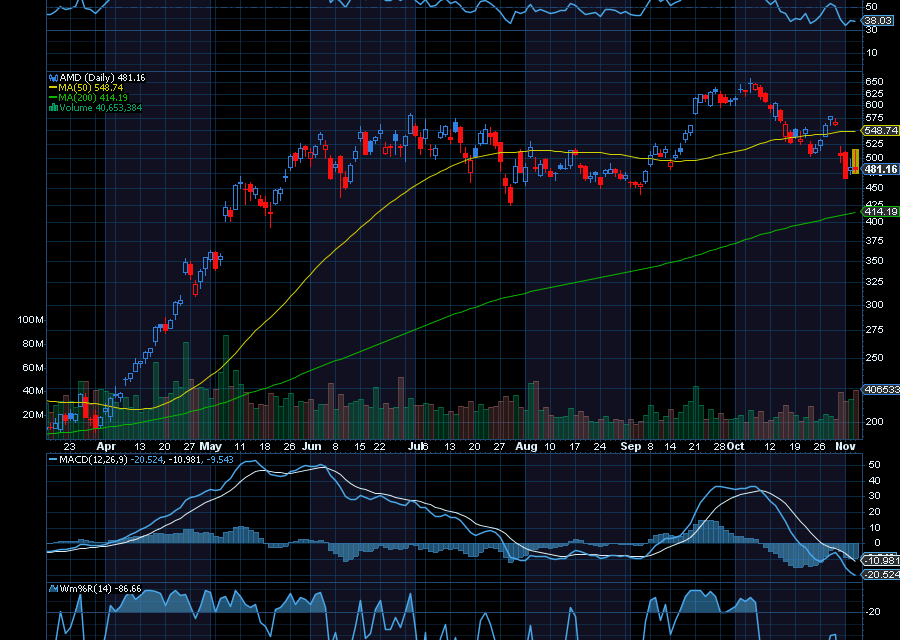
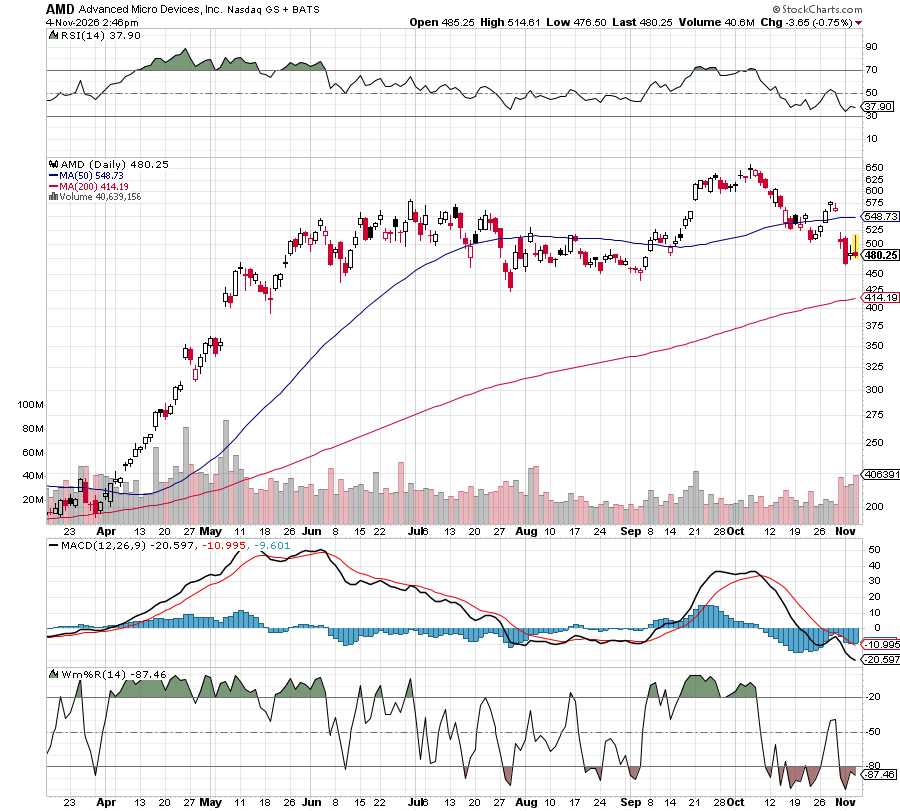
Oversold shares of AMD could see more upside.
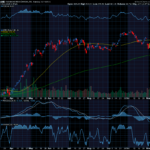
Last trading at $499.32, we’d like to see the tech giant rally back to $650.
Helping, the chipmaker beat Wall Street’s third-quarter earnings and revenue expectations. But the bigger attraction was its outlook. AMD expects demand for its data center products to keep climbing, potentially helping the company overcome a weaker personal computer market.
Strong Earnings Give Investors Something Concrete
For the third quarter, AMD reported adjusted earnings of $2.09 per share on revenue of $13.38 billion. Those figures topped the $1.95 per share and $13.09 billion analysts expected. The year-over-year performance was also impressive. Revenue increased 45%, while adjusted earnings per share climbed 74%. The company’s data center business led the way, with sales nearly doubling from a year earlier.
Put simply, Advanced Micro Devices is selling considerably more, and its adjusted profits are growing faster than its revenue. That gives investors something more concrete than enthusiasm about what artificial intelligence might eventually become.
Still, the latest quarter tells only part of the story.
AMD Sees Even Bigger Growth Ahead
Chief Executive Lisa Su told investors that server revenue is expected to double in 2027. She also indicated that growth in the company’s data center AI business could accelerate faster than the company anticipated three months earlier.AMD’s broader outlook calls for revenue growth of more than 80% in 2027. That is a substantial forecast for a company already generating billions of dollars in quarterly sales.
Sincerely,
Ian Cooper





Recent Comments